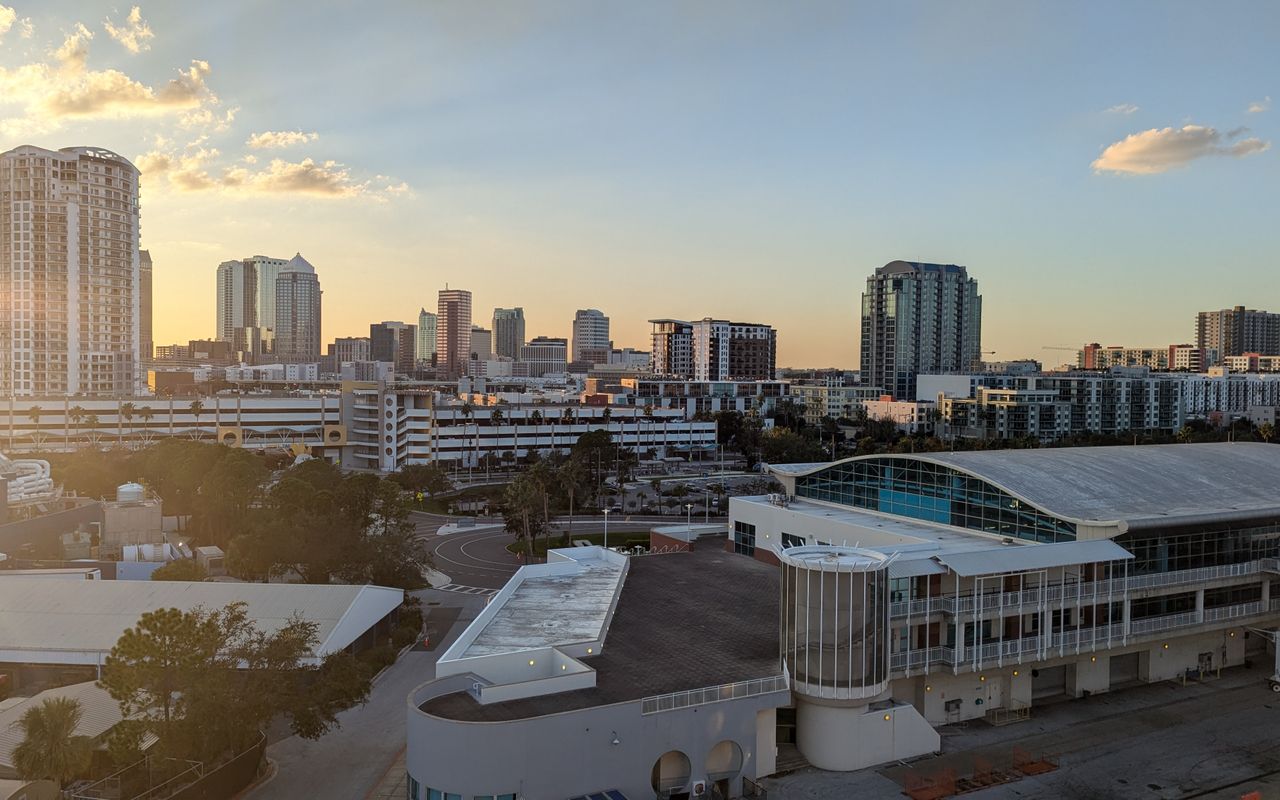
Mortgage guidance for Tampa, Florida.
Local market context, loan options, and honest answers for buying or refinancing in Tampa.
Buyers in Tampa commonly use conventional, FHA, VA, and jumbo financing. Tampa's diverse housing — from historic bungalows to luxury waterfront to new-construction townhomes — supports a broad range of programs.
- Tampa is the economic center of the Tampa Bay metro.
- MacDill AFB drives significant VA loan use.
- Housing spans historic, mid-century, and new-construction inventory.
- Jumbo financing is common along Bayshore and waterfront neighborhoods.
The Tampa market
Tampa is one of Florida's largest and most economically diverse cities. Finance, healthcare, technology, professional sports, port and logistics, and hospitality all contribute significantly. MacDill Air Force Base — home to U.S. Central Command and Special Operations Command — anchors a large military population.
Housing includes historic bungalows in Seminole Heights, Hyde Park, and Tampa Heights; mid-century blocks in South Tampa; luxury waterfront along Bayshore Boulevard and Davis Islands; new-construction townhomes and single-family in Riverview and New Tampa; and dense downtown/Water Street condos. Every major program is commonly used.
Who lives here
Tampa's identity blends historic Cuban and immigrant heritage (Ybor City), a strong sports culture, waterfront and river-oriented urban design, and a rapidly growing tech and business sector.
Tampa by the numbers
Current market conditions, Hillsborough County loan limits, and property tax context — pulled from federal and state sources rather than estimated, and refreshed on a schedule so the page ages honestly.
Hillsborough County loan limits — 2026
| Property | Conforming | FHA |
|---|---|---|
| 1 unit (single family) | $832,750 | $541,287 |
| 2 units (duplex) | — | $693,050 |
| 3 units (triplex) | — | $837,700 |
| 4 units (fourplex) | — | $1,041,125 |
Above the conforming limit, financing moves to a jumbo loan. VA loans have no county limit for eligible borrowers with full entitlement.
5.4608 millsHillsborough County general county levy, 2025
County millage is the general county operating rate only. Your actual bill also includes school, municipal, and special-district levies, and depends on assessed value, Save Our Homes caps, and any homestead or other exemptions you qualify for. Use this as directional context, not as an escrow quote.
Sources: Federal Housing Finance Agency — Conforming Loan Limits · U.S. Department of Housing and Urban Development — FHA Mortgage Limits · Florida Department of Revenue — Property Tax Data Portal · Last updated December 31, 2025. Figures are published reference data, not a quote or a commitment to lend. Vabasso Mortgage is an Equal Housing Lender.
Common home types in this market
Historic bungalows
Seminole Heights, Hyde Park, Tampa Heights.
Luxury waterfront
Bayshore, Davis Islands, Beach Park.
New-construction townhomes/single-family
Riverview, New Tampa.
Downtown condos
Channelside, Water Street.
Flood zones and insurance variation across Tampa's neighborhoods
Tampa's geography — a peninsula wrapped by Tampa Bay, Old Tampa Bay, and the Hillsborough River — means flood risk varies block by block rather than uniformly across the city. Bayshore Boulevard, Davis Islands, and low-lying parts of South Tampa carry meaningfully different flood-zone designations than inland neighborhoods like Carrollwood or New Tampa, and that determines whether flood insurance is required and how much it costs. A flood zone determination early in the process — not an assumption based on a neighborhood's general reputation — is the only reliable way to know what a specific property will require.
Wind coverage is a separate line item that applies regardless of flood zone, and both together are included in the qualifying payment a lender uses to size a loan. Buyers comparing a bay-adjacent home to an inland equivalent should request real insurance quotes for both before assuming the price difference reflects the full cost difference.
Financing options commonly considered here
Conventional and FHA handle the broad primary-residence market; VA supports MacDill families; jumbo covers waterfront and luxury; investment/DSCR support the strong rental market.
These are commonly considered programs — not a commitment to lend. Eligibility, pricing, and structure depend on your profile and the specific property.
Conventional Loan
The industry standard for home financing.
Explore program FHAFHA Loan
Accessible financing for first-time and lower-down-payment buyers.
Explore program VAVA Loan
The benefit veterans and service members have earned.
Explore program JumboJumbo Loan
Premium financing beyond conforming limits.
Explore program InvestmentInvestment Property Loan
Tailored programs for real estate investors.
Explore programRun the numbers before you decide.
Home Affordability Calculator
See a price range that fits your income, debts, and lifestyle.
Buying a HomeMortgage Payment Calculator
Estimate your monthly principal, interest, taxes, and insurance.
Buying a HomeDown Payment Calculator
See how different down payments affect your loan.
Buying a HomeClosing Cost Calculator
Estimate total costs to close on your home.
Investing & BuildingInvestment Property Calculator
Underwrite a rental with realistic assumptions.
Common questions about buying in Tampa
Is MacDill AFB in Tampa?
Yes. MacDill AFB is in South Tampa and drives significant VA loan use in the city.
Are jumbo loans common in Tampa?
Yes, particularly along Bayshore, Davis Islands, Beach Park, and other waterfront and luxury neighborhoods.
What loan fits a first-time buyer in Tampa?
FHA, conventional first-time buyer programs, and state/local down payment assistance programs are all commonly considered, depending on eligibility and income.
Can I finance a Tampa investment property?
Yes. Conventional investment property and DSCR programs are commonly considered, subject to lender guidelines.
How does Hillsborough County's flood mapping affect Tampa financing?
Tampa includes both low-risk inland neighborhoods and flood-zone areas near the bay, Hillsborough River, and Interbay Peninsula, so flood insurance requirements are property-specific rather than citywide. Lenders require flood coverage only when the specific address falls in a FEMA Special Flood Hazard Area, which a flood zone determination confirms during underwriting.
Are Tampa's downtown and Channelside condos warrantable?
It depends on the specific building — factors like investor concentration, commercial space, reserve funding, and any pending litigation determine whether a project meets standard agency guidelines. Newer Tampa high-rises with well-funded reserves are often warrantable, while older or investor-heavy buildings may require portfolio or non-warrantable condo financing.
How do HOA and CDD fees affect qualifying in Tampa's newer suburbs?
Community development district assessments, common in newer Tampa-area subdivisions, function similarly to a tax assessment and are added to the qualifying housing payment alongside any HOA dues. Two similarly priced Tampa homes can have different true monthly costs depending on whether one carries a CDD assessment and the other doesn't.
What are current mortgage rates in Florida for Tampa buyers?
Florida mortgage rates change daily with bond-market movements and borrower-specific factors. Vabasso Mortgage publishes live 30-year fixed, 15-year fixed, FHA, and VA benchmarks; a personalized quote gives the most accurate rate for your Tampa scenario.
What is the average mortgage payment in Florida for a Tampa home?
Payments vary by price, down payment, program, taxes, and insurance. Use Vabasso's mortgage calculator Florida suite to model a monthly payment for your Tampa purchase or refinance.
Can I use an FHA loan in Florida to buy in Tampa?
Yes. FHA loans are commonly used in Florida for first-time and repeat buyers who want a lower down payment and flexible credit guidelines. Eligibility depends on the property and borrower qualifications.
Can I use a VA loan in Florida to buy in Tampa?
Yes. Eligible service members, veterans, and qualifying spouses can use VA financing for primary residences in Tampa. VA loans typically offer competitive terms and may require no down payment for eligible borrowers.
Can I use a jumbo loan in Florida for a Tampa purchase?
Yes. Jumbo loans are commonly used in Florida when the loan amount exceeds conforming limits. In Tampa, jumbo financing is often used for luxury homes, waterfront properties, and high-price markets.
Mortgage Intelligence
How Much Home Can I Afford?
A practical framework for estimating an affordable home-price range using income, debts, down payment, taxes, insurance, and reserves.
Pre-Qualification vs. Pre-Approval
How the two most common early-stage mortgage steps differ, when each matters, and what documentation each generally requires.
How the Mortgage Process Works
A plain-language walkthrough of the mortgage journey from pre-qualification through closing.
Understanding Down Payments
How down payment size influences loan program eligibility, mortgage insurance, monthly payment, and total interest.
Mortgage Glossary
Ready to explore buying in Tampa?
Get pre-qualified in minutes, or ask Vabasso AI a question about your specific situation. A licensed advisor is available when you'd like to speak with a human.
Information on this page is educational and does not constitute a loan approval, rate quote, or commitment to lend. Eligibility depends on borrower, property, and program guidelines. Vabasso Mortgage is an Equal Housing Lender.